


Tom Sosnoff has spent more than four decades trading options, and he has a clear favorite: selling short strangles. It’s a strategy with limited profit potential and theoretically unlimited risk. Yet Sosnoff argues that, when managed properly, it can be less risky than many defined-risk alternatives.
In this Theta Profits interview, he explains his approach in detail, from choosing trades and selecting strikes to adjusting positions, taking profits, and managing losses.
Learn how Tom Sosnoff trades short strangles
Tom Sosnoff
Tom Sosnoff is one of the best-known personalities in options trading. A former Chicago options market maker, he founded thinkorswim and tastytrade and is now building Lossdog.
With around 45 years of trading experience, he remains an exceptionally active trader, sometimes placing 80–100 trades in a day, including adjustments and closing transactions.
Why Tom Sosnoff prefers short strangles
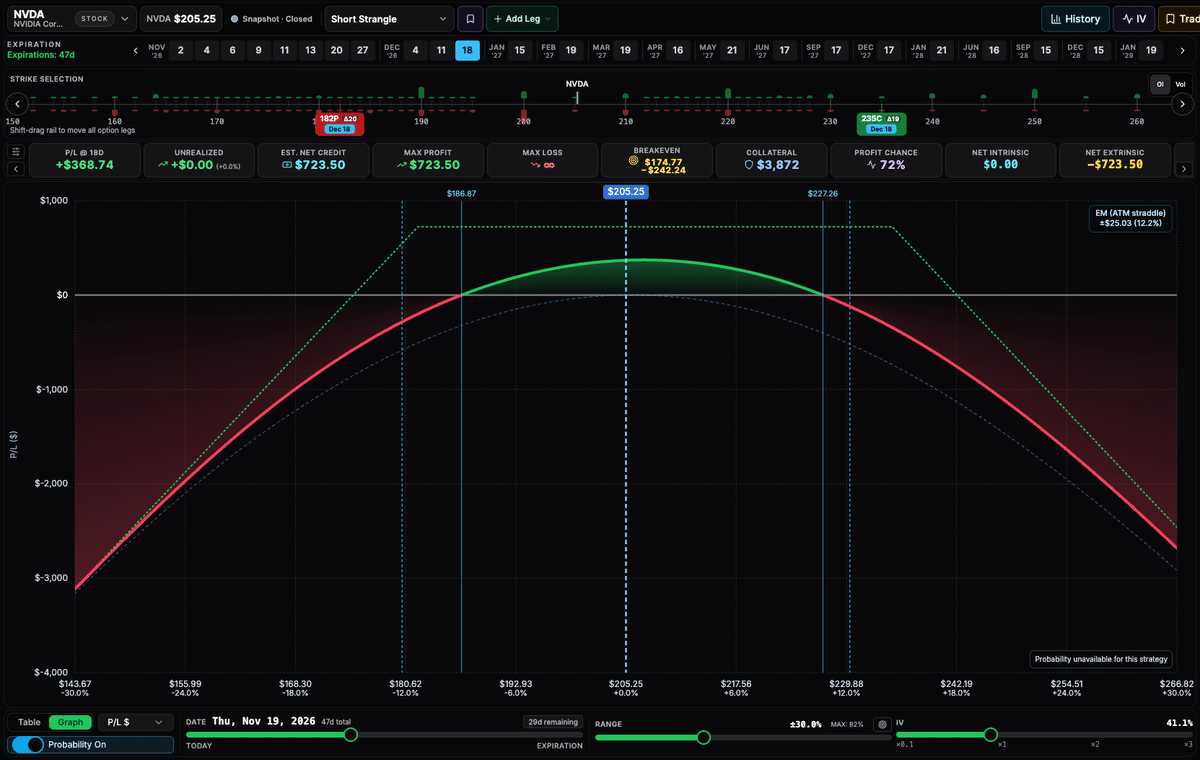
A short strangle involves selling an out-of-the-money put and an out-of-the-money call on the same underlying, typically with the same expiration date.
The trader collects premiums from both options and profits if the combined value falls sufficiently before closing the position. The maximum possible profit is the premium collected, while losses can be substantial if the underlying moves sharply in either direction. The short call creates theoretically unlimited upside risk.
Tom Sosnoff prefers selling both sides because he doesn’t claim to know where the market is heading.
By selling a put and a call together, he collects more premium than he would from selling just one side, without requiring additional buying power in his typical setup.
His approach is fundamentally a bet on mean reversion in implied volatility. He looks for situations where options premiums are relatively expensive and expects volatility to eventually decline.
Find the trades worth your time
SPONSORED MESSAGE: Options Matrix Pro is a web-based options research platform with live market data, short-options and advanced strategy scanners, a contract comparison matrix, a strategy visualizer and a trade journal.
How he selects trades: Liquidity, IV Rank and Delta
Tom Sosnoff follows several clear rules when opening short strangles.
1. Liquidity comes first
He avoids illiquid underlyings. Tight bid-ask spreads, good trading volume, and the ability to execute close to the midpoint are essential.
2. High Implied Volatility Rank (IVR)
Rather than focusing on absolute implied volatility, Tom uses implied volatility rank (IVR), which measures current implied volatility relative to its historical range.
His thresholds are straightforward:
- Below 30 IVR: He won’t open a position.
- Above 30 IVR: Acceptable.
- Above 50 IVR: Preferred.
3. Around 20 delta on each side
His typical starting point is selling options with approximately 20 delta. He associates this with a relatively high probability of success, while still collecting meaningful premium.
However, he doesn’t insist on perfectly balanced positions. He sometimes sells skewed strangles, with more delta on one side, reflecting a bullish or bearish bias.
4. Approximately 45 days to expiration
Tom considers 45 DTE close to ideal. It gives him time for the trade to develop, flexibility to adjust, and favorable conditions for time decay.
His preferred range is roughly 30–52 days.

Managing short strangles when the market moves
Trade management is central to Tom’s approach.
His main rule is surprisingly simple: Manage the trade when it makes you uncomfortable.
That discomfort might come from an unfavorable profit-and-loss position or from the position’s delta becoming too large.
His most common adjustment is rolling the untested side closer to the current market price.
For example, if the underlying falls, he may roll the short call down. If it rises, he may roll the short put up.
These adjustments collect additional premium and can reduce directional exposure.
When the strikes become too close together after repeated adjustments, he sometimes closes the existing strangle and opens a new one with wider strikes. He calls this buying the guts and selling the wings.
He also emphasizes that today’s low trading costs and efficient markets make frequent adjustments more practical than they were decades ago.
Taking profits and managing losses
Tom Sosnoff generally closes profitable trades at or before 50% of maximum profit.
His reasoning is straightforward: Trying to collect the final portion of the premium exposes traders to additional risk, particularly as expiration approaches.
He also follows a 21-DTE management rule. When a monthly position approaches 21 days to expiration, he typically rolls it into the next expiration cycle rather than allowing it to approach expiration.
His approach to losses is less mechanical.
Although his research suggests that closing at a loss of twice the initial credit can be mathematically favorable, he says the long-term difference compared with not using that rule is small.
Instead, he sometimes accepts a loss when he no longer wants to fight the position.
He also has one firm rule: If implied volatility rank falls below 20, he automatically closes the trade.
Unlimited risk: Why position size matters most
Perhaps the most provocative part of the interview is Tom’s perspective on risk.
He argues that unlimited theoretical risk doesn’t automatically make a strategy riskier than a defined-risk alternative.
His reasoning centers on probability of success, position sizing and active management.
For an average-sized account, he discusses keeping individual undefined-risk positions relatively small, often around 4–7% of account size in buying-power terms, with 10% as an upper limit.
Importantly, buying-power requirements are not a cap on potential losses. A short strangle can lose considerably more than the initial buying power required.
Tom also prefers reducing positions rather than adding separate hedges.
His message is consistent throughout the interview: trading too big is one of the most dangerous mistakes options traders make.
The biggest lessons from Tom Sosnoff
Tom Sosnoff’s approach combines relatively high-probability premium selling with frequent adjustments, early profit-taking, and disciplined position sizing.
He acknowledges that he has suffered substantial losses, including major losses from rising markets. But after 45 years, he continues to favor short strangles.
His broader advice applies well beyond this particular strategy: trade small, gain practical experience, explore different approaches, and don’t be afraid to manage positions early.
For traders considering undefined-risk strategies, the interview offers a detailed look at how one experienced trader approaches them — and why understanding and managing risk matters more than simply labeling a strategy safe or dangerous.

No backtest of these Tastytrade rules has ever shown a consistently profitable outcome, it only makes the broker rich. It has taken me a few years of losing big and crawling back again and again to understand that Tastytrade has not been honest in their research. When backtesting became available via Option Omega and others we could finally test these rules efficiently and to my surprise this strategy is a kind of breakeven game, which is ideal for a broker to endlessly milk their clients without them ever really quitting, because this strat keeps you rolling and rolling and rolling…